The Best Fluffy Pancakes recipe you will fall in love with. Full of tips and tricks to help you make the best pancakes.

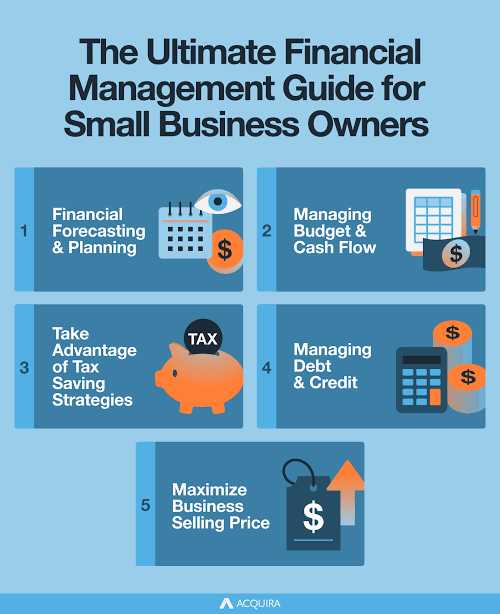
Most small business owners didn’t start their business because they love spreadsheets — they started it because they’re good at something else, whether that’s a product, a service, or an idea. But understanding business finance isn’t optional. It’s the difference between a business that survives its first few years and one that runs out of cash despite having plenty of customers.
This guide breaks down the core business finance concepts every owner should understand, without requiring an accounting degree to follow along.
Why Profitable Businesses Still Run Out of Money
One of the most common and dangerous misconceptions in small business is confusing profit with cash flow. A business can be profitable on paper — more revenue than expenses over a given period — and still run out of cash if customers pay late, inventory ties up money, or large expenses hit before revenue comes in. This mismatch, known as a cash flow gap, is one of the leading reasons small businesses fail even when demand for their product or service is healthy.
Understanding this distinction early is one of the most important financial habits a small business owner can build.
The Three Financial Statements Every Owner Should Understand
1. Income Statement (Profit & Loss)
Shows revenue, expenses, and profit over a specific period — usually monthly, quarterly, or annually. This is the statement most owners check first, but it only tells part of the story since it doesn’t show when cash actually moved in or out of the business.
2. Balance Sheet
A snapshot of what your business owns (assets), owes (liabilities), and what’s left over (equity) at a specific point in time. This statement is particularly useful for understanding overall financial health and is often what lenders review closely when evaluating a loan application.
3. Cash Flow Statement
Tracks the actual movement of cash in and out of the business, separated into operating, investing, and financing activities. This is arguably the most important statement for day-to-day survival, since it’s entirely possible to be profitable on the income statement while still being cash-poor in reality.
Managing Cash Flow: The Skill That Keeps Businesses Alive
Invoice promptly and follow up on late payments. The longer an invoice goes unpaid, the more likely it is to become a serious cash flow problem rather than a minor inconvenience.
Negotiate flexible supplier terms. Securing longer payment windows—even by a few weeks—can reduce short-term cash flow strain while leaving your underlying profitability unchanged.
Keep a cash reserve. Many financial advisors recommend maintaining enough cash reserves to cover three to six months of operating expenses, giving your business room to absorb slow periods or unexpected costs without immediately needing to borrow.
Forecast cash flow, not just profit. A simple 13-week rolling cash flow forecast — projecting expected cash in and cash out week by week — can catch a looming shortfall months before it becomes an emergency.
Understanding Business Funding Options in 2026
Interest rates for small business financing vary significantly depending on the type of loan and lender, so it’s worth understanding your options before you need one urgently.
SBA Loans — Backed by the U.S. Small Business Administration, SBA 7(a) loans currently carry maximum rates roughly in the 10–15% range depending on loan size and whether the rate is fixed or variable, while SBA 504 loans for major asset purchases like real estate or equipment often carry lower fixed rates, currently in the 5–6.5% range for long-term financing. SBA loans generally offer the most favorable terms available to small businesses, but qualification requirements and processing times are stricter than other options.
Traditional Bank Loans — Typically range from around 8% to 20% APR depending on creditworthiness, time in business, and revenue. Banks usually require at least two years in business and strong financials, making them a better fit for established businesses than brand-new startups.
Online and Fintech Lenders — Faster to fund, often within 24–72 hours, but at a meaningfully higher cost, with rates commonly ranging from 14% to 35% APR or more. These are best used for short-term needs where speed matters more than minimizing cost.
Business Lines of Credit — Rather than a lump sum, a line of credit lets you draw funds as needed up to a set limit, paying interest only on what you actually use — useful for managing seasonal cash flow gaps rather than funding a large one-time purchase.
Given how much rates vary by lender and loan type, it’s worth comparing multiple offers rather than accepting the first approval, since the difference between offers for the same loan amount can be substantial.
Budgeting for a Small Business
A simple, realistic budget matters more than a complex one you won’t maintain. At minimum, track:
- Fixed costs — rent, salaries, insurance, and other expenses that stay roughly the same each month
- Variable costs — inventory, materials, and other costs that scale with sales volume
- One-time or irregular expenses — equipment purchases, licensing renewals, or seasonal costs
- Revenue projections — based on realistic, historical data rather than best-case assumptions
Reviewing your budget against actual results monthly, rather than setting it once a year and forgetting about it, is what actually makes a budget useful rather than a formality.
Common Financial Mistakes Small Business Owners Make
Mixing personal and business finances. Beyond making bookkeeping harder, this can create tax complications and, for incorporated businesses, potentially jeopardize the legal protections that come with a separate business entity.
Underpricing products or services. Pricing based only on competitor rates, without accounting for your actual costs and desired margin, is one of the most common ways small businesses quietly erode their own profitability.
Ignoring financial statements until tax season. Reviewing financials only once a year means problems are often caught long after they could have been addressed.
Taking on debt without a repayment plan. Financing can be a legitimate growth tool, but borrowing without a clear plan for how the loan will generate enough return to cover repayment is a common path to financial strain.
Understanding Your Break-Even Point
Your break-even point is the level of sales at which your revenue exactly covers your total costs — beyond that point, additional sales start generating actual profit. Calculating it requires knowing your fixed costs, variable cost per unit, and price per unit, and it’s one of the most useful numbers a small business owner can know off the top of their head. Without it, decisions like “should I run this promotion” or “can I afford to hire another employee” become guesswork rather than informed choices grounded in your actual numbers.
A simple version of the formula: Break-Even Point (in units) = Fixed Costs ÷ (Price per Unit − Variable Cost per Unit). Revisiting this number whenever your costs or pricing change keeps it useful rather than letting it go stale.
Building Basic Financial Literacy as a Business Owner
You don’t need to become an accountant, but you should be able to read your own financial statements, understand your break-even point, and know your current cash position at any given time — not just at tax season. Many small business owners find it worthwhile to work with a bookkeeper or accountant for the technical work, while still staying personally involved enough to understand what the numbers are telling them, since ultimately those decisions are the owner’s responsibility, not the accountant’s.
If you’re just starting to build your broader financial foundation as a business owner, our business finance guide covers the wider picture of planning, budgeting, and long-term financial strategy that pairs well with the day-to-day basics covered here.
Frequently Asked Questions
What’s the difference between profit and cash flow? Profit measures revenue minus expenses over a period of time, while cash flow measures the actual movement of money in and out of your business. A business can be profitable but still cash-poor if payments are delayed or expenses are front-loaded.
How much cash reserve should a small business keep? A common guideline is three to six months of operating expenses, though the right amount depends on how seasonal or unpredictable your industry’s revenue tends to be.
What’s the cheapest way to finance a small business? SBA loans generally offer the lowest rates among financing options, though they come with stricter qualification requirements and longer processing times than online lenders.
Do I need an accountant if I’m just starting out? Not necessarily from day one, but as revenue and complexity grow, most owners benefit from at least periodic guidance from a bookkeeper or accountant, even if they handle day-to-day finances themselves.
Conclusion
Business finance doesn’t have to be intimidating — it comes down to a few core habits: understanding the difference between profit and cash flow, keeping a realistic budget, maintaining a cash reserve, and choosing financing options deliberately rather than out of urgency. Building these habits early gives a small business a much stronger foundation to grow from, regardless of the industry.
For official guidance on small business loans and current SBA rate information, the U.S. Small Business Administration’s official financing page is the most authoritative source available.